Advances in Bioengineering and Biomedical Science Research(ABBSR)
ISSN: 2640-4133 | DOI: 10.33140/ABBSR
Impact Factor: 1.7
Review Article - (2024) Volume 7, Issue 2
The Impact of Boardroom Diversity on Company Performance Using Propensity Score-Based Estimators (PSM)
2Economics Department at the University, Rwanda
Received Date: Mar 08, 2024 / Accepted Date: Mar 25, 2024 / Published Date: Apr 29, 2024
Copyright: ©Â©2024 Clement Uwizeye. This is an open-access article distributed under the terms of the Creative Commons Attribution License, which permits unrestricted use, distribution, and reproduction in any medium, provided the original author and source are credited.
Citation: Uwizeye, C. (2024). The Impact of Boardroom Diversity on Company Performance Using Propensity Score-Based Estimators (PSM). Adv Bioeng Biomed Sci Res, 7(2), 01-05.
Abstract
This study investigates the impact of boardroom diversity on firm performance utilizing propensity score- based estimators (PSM). Drawing from a comprehensive literature review, it is established that gender diversity in boardrooms positively influences firm performance, particularly in the financial sector. Using panel data from 503 UK firms over the period of 2015-2017, the analysis focuses on key performance indicators such as market capitalization and leverage. Employing various econometric models, including binary treatment and augmented inverse-probability weighting, the study reveals significant positive effects of female board- room participation on firm performance. Specifically, an increase in female representation is associated with higher market capitalization and an increased leverage ratio, indicating a propensity for riskier investments. Furthermore, the study explores the nuanced effects of different levels of female director representation, highlighting the importance of substantial gender diversity for optimal firm performance. Despite potential limitations such as treatment selection bias and omitted variable bias, the models demonstrate robustness and contribute to the existing literature by providing empirical evidence supporting the positive impact of boardroom diversity on company performance.
Keywords
Boardroom Diversity, Firm Performance, PSM, Gender Diversity, Financial Sector
JEL Classification: M14, L20, J16;G301
Introduction
Boardroom diversity, particularly in terms of gender representation, has garnered significant attention in recent years as companies strive to enhance their decision-making processes and overall performance. This study delves into the impact of boardroom diversity, specifically focusing on the presence and influence of female directors, on company performance using Propensity Score-Based Estimators (PSM). A thorough investigation of the existing literature reveals a mix of findings regarding the relationship between gender diversity in the boardroom and firm performance. Some studies, such as, emphasize the positive influence of female directors on firm performance, while others, like, suggest a negligible impact [1,2]. However, the consensus among researchers points towards a significant positive association between gender diversity in the boardroom and enhanced firm performance, especially in sectors like finance.
Literature Investigation
An increasing number of companies have recognized the importance of increasing the number of females on their decision-making teams. While some recent research shows that gender diversity affects organizational performance, others have been ambiguous.
Canyon and He (2015) used a sample of more than 3000 US firms between the years of 2007 and 2014 for their study on firm performance and boardroom gender diversity (BGD) [1]. It was shown that female directors have a significantly higher and positive effect on performance using the quantile regression approach. This suggests that the female directors’ leadership is a key factor in the success of these high-performing companies, implying that companies should put more effort into ensuring the best female candidates are appointed to positions of power rather than just meeting a quota since BGD is particularly beneficial to successful businesses. For the measure of performance, the authors used Tobin’s Q as market-based performance and return on assets as accounting-based performance.
In another study, Chen et al. (2017) observed the effect of boardroom gender (BG) composition on payment pay-out using an illustration of 12,050 firms’ observations from 1997 to 2011 [3]. Using the PSM, DiD, and IV approaches, they discovered that BG composition significantly increases payment pay-out only for companies with poor governance, implying that female directors use payment distributions as an authority tool. This outcome demonstrates the significant role that female directors play in corporate authority and suggests that the gender diversity of the board should be considered when assessing corporate performance. Isola et al. (2020) focused on the representation of women in boardrooms using 14 banks that were listed on the Nigerian Stock Exchange (NSE) between 2008 and 2017 [2]. The results of the Hausman test and the random effects (RE) technique showed that while intellectual capital efficiency positively affects bank performance, female boarding contribution has a negligible impact on bank performance. This study supports earlier research which found that while intellectual capital efficiency positively correlated with firm performance, female boardroom participation did not. In their study about BGD and CEO pay relation Ahmed et al. (2021) use a sample of 2,288 respondents from Australian firms in the period from 2006-2014. The authors used ROA, ROE, and BFP to measure firm performance. The authors found that BGD was negatively related to CEO pay deviation, indicating that companies with gender-diverse boards are wary of the 2 effects of CEO pay deviation (under/overpaying) and are therefore more willing to bridge the gap.
Kinateder et al. (2021) investigate whether BGD reduces credit risk in the financial sector [4]. From 2006 to 2017, banks in 20 countries were examined using global evidence. We discovered that increasing BGD by one standard deviation increases the reserve to evasion, bankruptcy, and capital. The following methods were used: two-stage least squares regression, DID, and PSM investigation. According to these findings, gender diversity in the boardroom can improve a bank’s financial performance. From 2013 to 2017, Shakil et al. (2021) studied BGD and eco-friendly, community, and authority performance of US banks: the moderating role of eco-friendly, community, and corporate authority controversies with a sample of 37 US banks [5]. The results of the GMMs show that Environmental, Social, and Governance (ESG) controversies have no moderating effect on the BGD-ESG presentation link. According to the authors, the presence of a gender-diverse board of directors was found to be significantly associated with improved environmental, social, and governance performance. To measure the performance, the authors used the mean leverage ratio and return on assets.
To conclude this section, the majority of researchers conclude that gender diversity on boards has a significant positive impact on the performance of firms, particularly in the financial sector, and that the environment in which they work may determine the extent of their performance. In order for the potential positive effects of gender diversity on the board performance to be realized, corporate governance must include strategies that support and promote gender diversity in the boardroom for high-level performance and development.
Descriptive Statistics
For the econometric approach, this analysis uses a panel data set covering three periods from 2015 to 2017. During this time, 503 firms in the UK were questioned regarding their boardroom characteristics and key business figures to measure their performance. For easier understanding, variable names are given in brackets. The key variable for this analysis is boardroom diversity which is measured as the “number of female directors” (N female) in each year. The data reveals that there were zero female directors in 2015. An exogenous shock in 2016 led to an increase in female participation in boardrooms with more than 55% of all firms increasing their diversity (binary female 2016). Since it is hard to stop the patriarchy in only one year, only 5 firms were able to increase the share of female directors among all directors to above 50%, and half of the firms only have a female share of below 20% (share female). Overall, the 289 treated firms can be categorized into different groups of the same size to identify the effects of different percentiles (cat female 2016, cat 50 female 2016, and cat 20 female 2016).
As a way to measure firm performance, this analysis considers the two most used business figures as ex- plained in the literature section: market capitalization and leverage. Logged market capitalization (d lnMV) will be our main outcome variable since the interpretation is straightforward as it displays the size of the company. Financial leverage (d leverage) identifies the debt ratio of the firm and is defined as the share of total debt on shareholder´s equity. Although the effect on firm performance is hard to interpret since a high debt ratio can lead to a positive leverage effect and finally increase the return on equity, lowering the debt ratio is often considered as a way to decrease risk. All variables are created using differences over time to eliminate unobserved time-invariant confounders affecting firm performance (relative to pre-treatment).
To get a first idea of which firms we are looking at, a simple logarithmic regression of female boardroom participation (binary female 2016) on all available boardroom performance variables is performed. In addition, we include squared terms for all metric boardroom variables. The performance variables, although most of them are metric, are not being squared since the interpretation is not straightforward due to reversed scales or negative 3 values in some cases. For example, a high Tobin´s Q is not desirable since the company would appear to be very overvalued. Instead, we use the absolute distance to 1 to include it into the regression which is what firms are aiming to minimize. To improve regression results we neglect the squared term of average director age since a very high director age has a high correlation with tenure as the directors have a high probability of staying in the company for a long time.
The data shows that the pre-treatment characteristics of treated and untreated firms are significantly different for many performance and boardroom variables. An interesting pattern of the underlying data is, for example, that the number of directors is only beneficial for female boardroom participation if the number is sufficiently high as seen in the positive effect for the squared term and a negative effect for the variable itself. Another interesting point in the data is that the number of nations represented in the boardroom, which might be a proxy for the globalization of the company, has no effect on the treatment status.
In order to get a first glance at potential regression results, we perform an OLS regression with our performance variables as explanatory variables. Although the change in market capitalization or the leverage ratio is not an overall measure of firm performance, they are mostly independent from other performance indicators like cash flow or Tobin´s Q. This is why we can use not only the boardroom characteristics but also the performance variables to explain the variation of our explanatory performance variables. The regression shows that the effect of female participation as a binary treatment has a positive effect on the market capitalization and increases the leverage ratio.
The Model
This study uses treatment effects as an econometric approach to identify the causal effect of boardroom diversity. This approach is preferable since the arrival of female directors in 2016 can be interpreted as a treatment. Thus, in section 3 we work with a binary treatment splitting the firms into two groups of treated and untreated, and in section 4 the treatment group is split further to identify patterns of boardroom diversity.
A major problem of this study might be the serious treatment selection problem since female boardroom participation cannot be randomly assigned by governments and thus, firms do have some control over the treatment assignment mechanism. This would ultimately impose a bias to the resulting treatment effects but for the sake of this training exercise, we ignore this fact and continue as if the treatment is assigned randomly. Although section 2 showed that there are great differences pre-treatment, it also indicates that we can account for a lot of observable confounders as seen in a very high pseudo R2. Even without yet considering the covariates balance tests, this might already be a first indication that, at least while conditioning on X, we can show that the treatment variable is independent of a potential outcome and sufficiently ensure the conditional independence assumption.
To ensure the stable unit treatment value assumption, we test for possible contagion and diffusion patterns. The first is hard to test due to the way how boardroom diversity influences the performance of the firm. The latter might have some implications for our dataset since there are some sectors, for example, transport and construction, in which the share of treated firms is higher than 85% and thus possibly dilute any competitive advantage it might have.
For this section, the nearest-neighbor matching estimator is used as a way to match treated and untreated firms based on their propensity scores. In our first model, we begin by applying this estimator for the two nearest neighbors’ cases to estimate the average treatment effect of boardroom diversity on market capitalization and the leverage ratio. We use a logit model to predict treatment status as a function of certain boardroom characteristics and performance indicators which had the highest explanatory power in the logit model in section 2 and control for the respective sector (a detailed summary of covariates can be found in Appendix 1). For both outcome variables, the overlap assumption is violated for one observation. We re-estimate the model using only the observations which are not violated by the overlap assumption. Unfortunately, both outcome variables are insignificant for our treatment variable. Applying the covariates balance test shows that the selection of variables based on earlier logit regressions are beneficial and most variables show a decent balance but there is still room for improvement. However, plotting the overlap between treated and untreated reveals that there is a substantial gap potential resulting from significantly different pre-treatment characteristics between treated and untreated firms.
In our second model, everything is kept constant but the treatment prediction model is changed to probit. The overlap violations remain similar to the first model setting. While the covariates balance and significance of our first performance variable, market capitalization, does not seem to profit from this model change, our second variable, leverage ratio, shows improvement. Estimates indicate that boardroom diversity, measured binary, leads to an average treatment effect of 0.05 points on the difference between leverage ratios of 2017 and 2015. Thus, boardroom diversity leads to more risky investments but also increases the usefulness of the leverage effect.
In our third model, probit is kept as the treatment prediction model, but the number of possible neighbors is increased to four. This heightens efficiency gains, but also the potential danger of matching dissimilar pairs. In this setting, only the market capitalization shows a significant effect while obtaining a decent covariate balance. Since the difference between the two logarithmic values is hard to interpret, the left-hand side of our equation is rearranged to use the logarithmic ratio of 2017 and 2015 as the outcome.
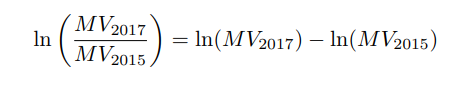
Now the estimated value can be interpreted as follows: The treatment increases the ”ratio” between the market capitalization of 2017 and 2015 by 18.6%, on average ceteris paribus.
In our fourth model, we introduce caliper matching, which is a pre-specified tolerance level to decrease the risk of pairing up bad matches if the nearest neighbor happened to be far away. However, it turns out that a low tolerance level of 0.1 decreases the number of matches significantly, and a higher tolerance level of 0.2 does not change the estimated effects of model 3 significantly.
In the last model of this section, we interact the board room characteristics with the performance measures based on the second (probit) model. This model seems to have the biggest explanatory power since both outcome variables show highly significant treatment effects but also a better covariates balance test than in the other regressions. The average treatment effects show only marginal differences from the measured effects in the earlier models and are therefore not presented again. However, by using this interaction, the number of observations that have to be neglected due to overlap violation increases in both cases. Finally, even though the choice of regressors is questionable since it is not as clear as in the earlier models, this setting seems to be the most favorable setting as both the significance of the treatment variable and the covariates balance test seem to improve from including these interactions.
Robustness Checks
The models from section 3 provide a clear indication that female boardroom participation increases firm performance in comparison to firms without any boardroom diversity. However, what is missing from these models is the share of female directors among the total number of directors. To be precise, we continue by testing whether there is a different effect of a high female share compared to a low female share in boardrooms. For this purpose, a different type of estimator has to be introduced, which can estimate non-binary treatment variables. The augmented inverse-probability weighting not only serves this purpose but also lowers the possibility of selection bias, which was shown in section 2. The estimator works by combining covariates-adjusted regression with inverse probability weighting and, therefore, as long as either the conditional regression function or the propensity score model is correctly specified, it can provide unbiased inference under model misspecification. As shown in section 3, at least the propensity score model is correctly specified in our case, and therefore we can expect unbiased inference.
In the following model, a linear regression is performed to model the performance outcome of the change in market capitalization and the change of the leverage ratio from 2015 to 2017. It appears that to sufficiently predict this model, more performance variables have to be included compared to models in section 3. This is justified since, for example, for the estimation of the change in market capitalization, most performance variables have a higher influence in predicting future performance than the decision to include female directors. In addition, in the model to predict the treatment status, the number of directors is eliminated since the treatment variable itself already contains this information. The new covariates are stated in Appendix 3.
Starting with the change in market capitalization when splitting the treated into two categories with each 50% of the observations, it can be observed that both effects are significant and positive as predicted by the last model in section 3, and that the effect is higher for a larger share of female boardroom participation. When continuing with the categorization of 3 groups of the same size, it can be noted that the effect of the lowest category is insignificant while the other categories show similar increases as in the model specification above. If we go a step further and categorize the treatment variable into 5 groups, we see that for the lowest group, which contains all firms with a share of at most 15% of female directors among total directors, the average treatment effect even becomes negative, implying a decrease in market capitalization.
Thus, the results suggest that the discussion of a non-binary treatment is important since an increasing share of boardroom diversity can benefit market capitalization. However, the regression also shows that desirable effects of boardroom diversity are not achieved when only hiring one woman (e.g., to maintain the appearance of diversity).
In comparison, the effects of the leverage ratio are related even less to the share of female boardroom participation. Using the second model specification of this section with three groups shows that the effects for each category are very similar and no trend is visible. However, as the estimated potential outcome means indicate, the effects are still significantly different from a non-treated firm.
Conclusion
The findings of this study are in line with the current literature indicating that female boardroom participation has a highly positive effect on key performance measures of the firm.
In the third section, we analyzed the question of whether any female boardroom participation, regardless of their size, can increase market capitalization and found a positive effect. In addition, we found that these firms also have a higher chance of investing with external capital since the leverage ratio increased. Building upon these findings, section 4 explores how the share of female directors among total directors might influence our findings. We found that when it comes to market capitalization there is a clearly identifiable trend that is increasing with the rate of gender diversity. However, employing only a low share of female directors can even lead to negative results. Concerning the development of the leverage ratio, no trend in the effect of the female director share can be observed. Finally, the model looks well-specified and serves the desired purpose. Beside the treatment selection problem due to the exercise, possible shortcomings are unclear spill-overs and a the potential omitted variable bias which lowers the predictive power of the treatment model as discussed in section 3.
Conflict-of-Interest Disclosure
The author declares that he has no conflicts of interest related to this research.
References
- 1.Conyon, M. J., & He, L. (2017). Firm performance and boardroom gender diversity: A quantile regression approach. Journal of Business Research, 79, 198-211.
- 2.Isola, W. A., Adeleye, B. N., & Olohunlana, A. O. (2020). Boardroom female participation, intellectual capital efficiency and firm performance in developing countries: Evidence from Nigeria. Journal of Economics, Finance and Administrative Science, 25(50), 413-424.
- 3.Chen, J., Leung, W. S., & Goergen, M. (2017). The impact of board gender composition on dividend payouts. Journal of Corporate finance, 43, 86-105.
- 4.Kinateder, H., Choudhury, T., Zaman, R., Scagnelli, S. D., & Sohel, N. (2021). Does boardroom gender diversity decrease credit risk in the financial sector? Worldwide evidence. Journal of International Financial Markets,Institutions and Money, 73, 101347.
- 5.Shakil, M. H., Tasnia, M., & Mostafiz, M. I. (2021). Board gender diversity and environmental, social and governance performance of US banks: Moderating role of environmental, social and corporate governance
Appendix
- Covariates for the treatment status of boardroom diversity (section 3): tenure 2015, tenure 2 2015, age 2015, N dir2015, N dir 2 2015, lnMV 2015, one TobinQ 2015, Leverage 2015 and sector 2015.â??â??â??â??â??â??â??
- Covariates to model performance outcomes (section 3): age 2015, age 2 2015, N nations 2015, N dir 2015,N dir 2 2015, lnMV 2015, Cash 2015, one TobinQ 2015,controversies. International Journal of Bank Marketing, 39(4), 661-677.
- Ahmed, A., Atif, M., & Gyapong, E. (2021). Boardroom gender diversity and CEO pay deviation: Australian evidence. Accounting & Finance, 61(2), 3135-3170.Leverage 2015, R Ya 2015 and sector 2015.
- Covariates for the treatment status of boardroom diversity (section 3): tenure 2015, tenure 2 2015, age 2015
- Covariates to model performance outcomes (section 4): tenure 2015, tenure 2 2015, age 2015, lnMV 2015,
- Cash 2015, one TobinQ 2015, Leverage 2015, R Ya 2015and sector 2015.